Taking the $300,000 contract puts $66,000 of margin on the table, but the job's cash drops to -$103,500 by the end of month 2 and stays below zero until month 7. Turning it down keeps the cash safe and gives up the margin. Whether to take it depends on whether you can find $103,500 before the first payment comes in.
| Month | Cash out | Cash in (net of retainage) | Running cash |
|---|---|---|---|
| 1 | $60,000 | $0 | -$60,000 |
| 2 | $43,500 | $0 | -$103,500 |
| 3 | $43,500 | $54,000 | -$93,000 |
| 4 | $43,500 | $54,000 | -$82,500 |
| 5 | $43,500 | $54,000 | -$72,000 |
| 6 | $0 | $54,000 | -$18,000 |
| 7 | $0 | $54,000 | +$36,000 |
| 8 | $0 | $30,000 | +$66,000 |
| Total | $234,000 | $300,000 | $66,000 margin |
The number to fund is the lowest point on the running cash line, -$103,500, because the $66,000 of margin only shows up months after the money has gone out.
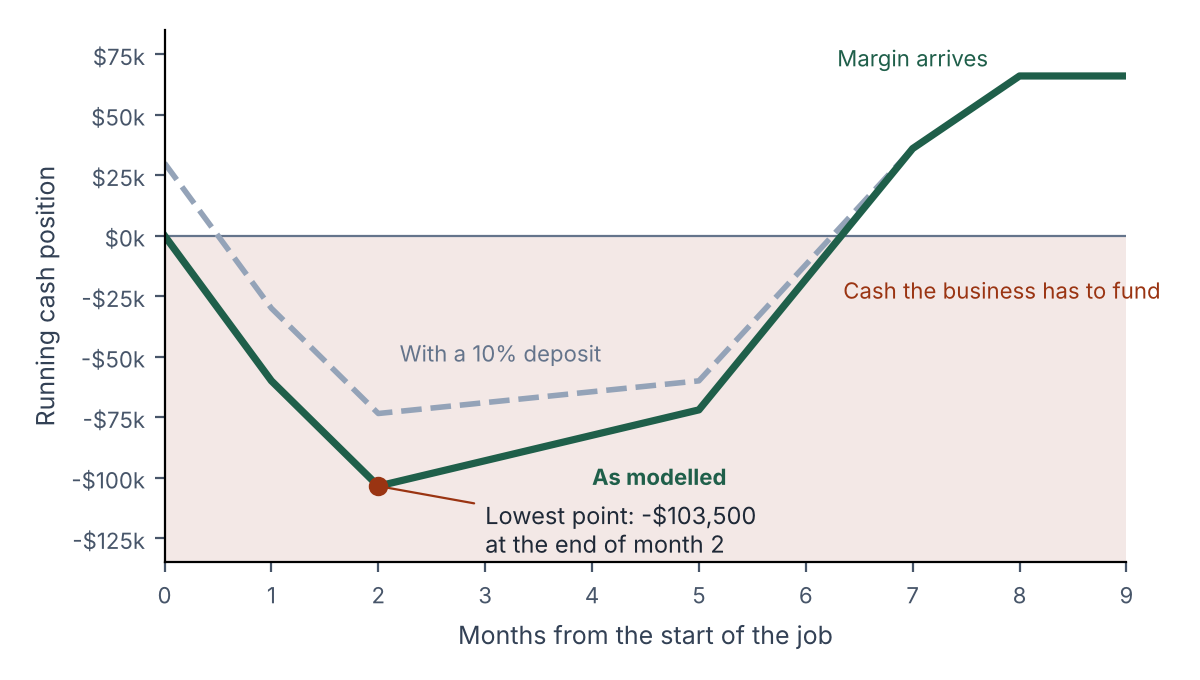
This contract and its numbers are made up to show the arithmetic. The inputs and their basis are under "How this example is built" at the end.
What shrinks the gap
| Change, one at a time | Low point | Change |
|---|---|---|
| As modelled | -$103,500 | none |
| 10 percent deposit ($30,000) paid before work starts, credited against the invoices | -$73,500 | +$30,000 |
| Net-30 instead of net-45 (the +$43,500 is an upper bound on the improvement: net-45 is rounded up to 2 months, net-30 is exactly 1) | -$60,000 | +$43,500 |
| Invoice twice a month | -$103,500 | $0 |
A change helps only if it moves cash in before the low point. Twice-monthly invoicing does not here: the first payment still lands after month 2's costs. The deposit is a contract term paid before work starts, so it has to be asked for before signing.
What late payment does
| Payments arrive | Low point | Still to find after $40,000 in the bank |
|---|---|---|
| As modelled | -$103,500 | $63,500 |
| 30 days later | -$147,000 | $107,000 |
| 60 days later | -$190,500 | $150,500 |
Each month of delay moves the low point later and deeper. The cash balance is in the inputs table; payroll and overhead the business already carries come on top.
What borrowing the gap costs
Interest of about $2,000 to $4,300 against $66,000 of margin is small, so the decision turns on whether the cash can be had and on late payment, not on the rate.
| Deposit | Annual rate | Cash to find | Interest | Share of contract | Margin left |
|---|---|---|---|---|---|
| None | 8 percent | $103,500 | $2,860 | 1.0 percent | $63,140 |
| None | 10 percent | $103,500 | $3,575 | 1.2 percent | $62,425 |
| None | 12 percent | $103,500 | $4,290 | 1.4 percent | $61,710 |
| $30,000 | 8 percent | $73,500 | $2,060 | 0.7 percent | $63,940 |
| $30,000 | 10 percent | $73,500 | $2,575 | 0.9 percent | $63,425 |
| $30,000 | 12 percent | $73,500 | $3,090 | 1.0 percent | $62,910 |
| Line of credit sized to | Amount | Against the low point of $103,500 |
|---|---|---|
| Month 1's costs | $60,000 | Used up in month 2, $43,500 short, with three months of work to go |
| The low point exactly | $103,500 | Enough only if no payment slips |
| The low point plus a 20 percent buffer | $124,200 | $20,700 spare, less than the $43,500 that a 30-days-late payment adds |
| The 30-days-late low point | $147,000 | Covers the late case with nothing spare |
Swap in the rates the bank offers and the buffer you would want. The interest basis is in the inputs table.
When the other choice is right
| Take it as written when | Decline or reprice when |
|---|---|
| Cash plus a line the bank has approved covers the low point, including the 60-days-late row | No combination of deposit, terms and credit covers the low point |
| The contract charges the customer for paying late | Late payment costs the customer nothing, so the 30 and 60 day rows are the likely case |
| The customer is a small share of revenue | The customer is a large share: $300,000 is 25 percent of an example $1,200,000 business |
| Job-level costs are current enough to forecast from | The books are months behind, so no forecast can be built |
Before signing
- Tax: the figures are before tax. Ask the accountant how much of the interest reduces taxable profit and when the margin is taxed, then compare taking and declining after tax.
- Contract terms: retainage, deposits and late-payment rights differ by state and contract. Ask a business attorney to read them.
- Who does what: a controller builds the weekly cash forecast, the banker sizes the line, and the attorney reads the payment terms.
Before you say yes to a job this size, get the month-by-month cash line and size your commitment by its lowest point. Here that is $103,500, well past the $60,000 the first month costs.
To test a contract with its own numbers, use the contract affordability calculator. If it is unclear whether the problem is timing, margin or books, the profit-cash diagnostic takes about three minutes. For a 1:1 review, email [email protected] with the contract value, payment terms, current cash and credit line.
How this example is built
| Input | Value | Basis |
|---|---|---|
| Contract | $300,000 | Five months of work |
| Direct costs | $234,000, 78 percent of the contract | $60,000 in month 1, $43,500 in each of months 2 to 5 |
| Margin | $66,000 | Contract minus direct costs, before the business's own overhead |
| Invoices | $60,000 at each month end | Five equal invoices, months 1 to 5 |
| Retainage | 10 percent of each invoice, $30,000 in all | Held back by the customer, released at the end of month 8 |
| Payment time | 45 days | Modelled as the end of the second month after the invoice (the cautious round-up) |
| Deposit | $30,000, 10 percent of the contract | Paid before work starts, credited evenly against the five invoices |
| Cash already in the bank | $40,000 | For this contract alone |
| Size of the business | $1,200,000 of revenue | For the share-of-revenue row |
| Borrowing | Interest at 8, 10 and 12 percent a year | Rates to compare; charged on the average balance drawn over months 1 to 6 |
This article is informational and does not constitute financial, legal, or tax advice. Consult a qualified professional for decisions specific to your situation.